
It is a Saturday afternoon on Morse Road. You have test-driven three cars, settled on one, and shaken hands on a price. Then the finance manager slides a form across the desk and asks a question you did not plan for: "Who is your insurance with? We will need proof before you take it home."
For a lot of buyers, that one question turns a two-hour visit into a four-hour one. The good news is that it is completely avoidable. Here is how insurance fits into buying a car in Ohio, what the dealership is likely to ask for, and how to have it handled before you ever sit down to sign.
Ohio Law Requires Insurance Before You Drive
Ohio does not let you drive first and insure later. Under Ohio Revised Code 4509.101(A)(1), no one may operate a motor vehicle in Ohio, or permit it to be operated, unless proof of financial responsibility is maintained continuously for that vehicle. For almost everyone, "financial responsibility" means an auto insurance policy.
Ohio's minimum liability limits are set in ORC 4509.51(B):
$25,000 for bodily injury or death to one person in an accident
$50,000 for bodily injury or death to two or more people in an accident
$25,000 for damage to property in an accident
Those numbers are the legal floor, not a recommendation. They are the least you can carry to drive legally, and a serious accident can cost far more than that. We will cover how to choose limits in a later post.
One detail surprises many buyers. The temporary tag the dealer hands you is issued on proof of purchase alone. ORC 4503.182(A) makes a temporary registration valid for 45 days, and nothing in that section requires proof of insurance to issue it. So a temp tag in the back window does not mean the car is insured. That part is on you.
Driving without coverage has real consequences. A first violation of 4509.101 carries a license suspension under division (A)(2)(a), along with reinstatement requirements before you can drive again.
What the Dealership Will Usually Ask For
What the dealer needs depends mostly on how you are paying.
Paying cash: Some dealers will still ask to see coverage before you leave, because the car is being driven off their lot. Even if they do not ask, Ohio law requires it the moment you drive.
Financing or leasing: Expect to show proof. Lenders almost always require you to carry comprehensive and collision coverage on the car and to list the lender on the policy as the lienholder. Many lenders want that proof before they will fund the loan, which is why the dealership needs it before delivery.
The proof itself is usually an insurance ID card or the declarations page showing the new car's VIN. If you are financing, the declarations page should also show the lender's name and address. Ohio law allows you to show proof electronically on your phone under ORC 4509.101(G)(1)(b), so an emailed or app-based ID card works for a traffic stop. Your dealer or lender may still want a copy sent to them directly.
Already Have a Policy? Do Not Assume It Moves With You
If you already insure a car, you might assume your policy automatically covers the new one. Sometimes it does, for a short window, and sometimes it does not. The answer depends on your specific policy, whether the new car replaces your old one or is an addition, and which coverages you carry today.
Lenders also do not accept "my policy probably covers it." They want to see the new VIN and their name on the declarations page. The safest move is simple. Call or text your agent before you drive the new car, and have the car added with the lender listed. We will walk through how newly acquired vehicle coverage works, and how to handle a trade-in, in an upcoming post.
What to Have Ready for a Quote
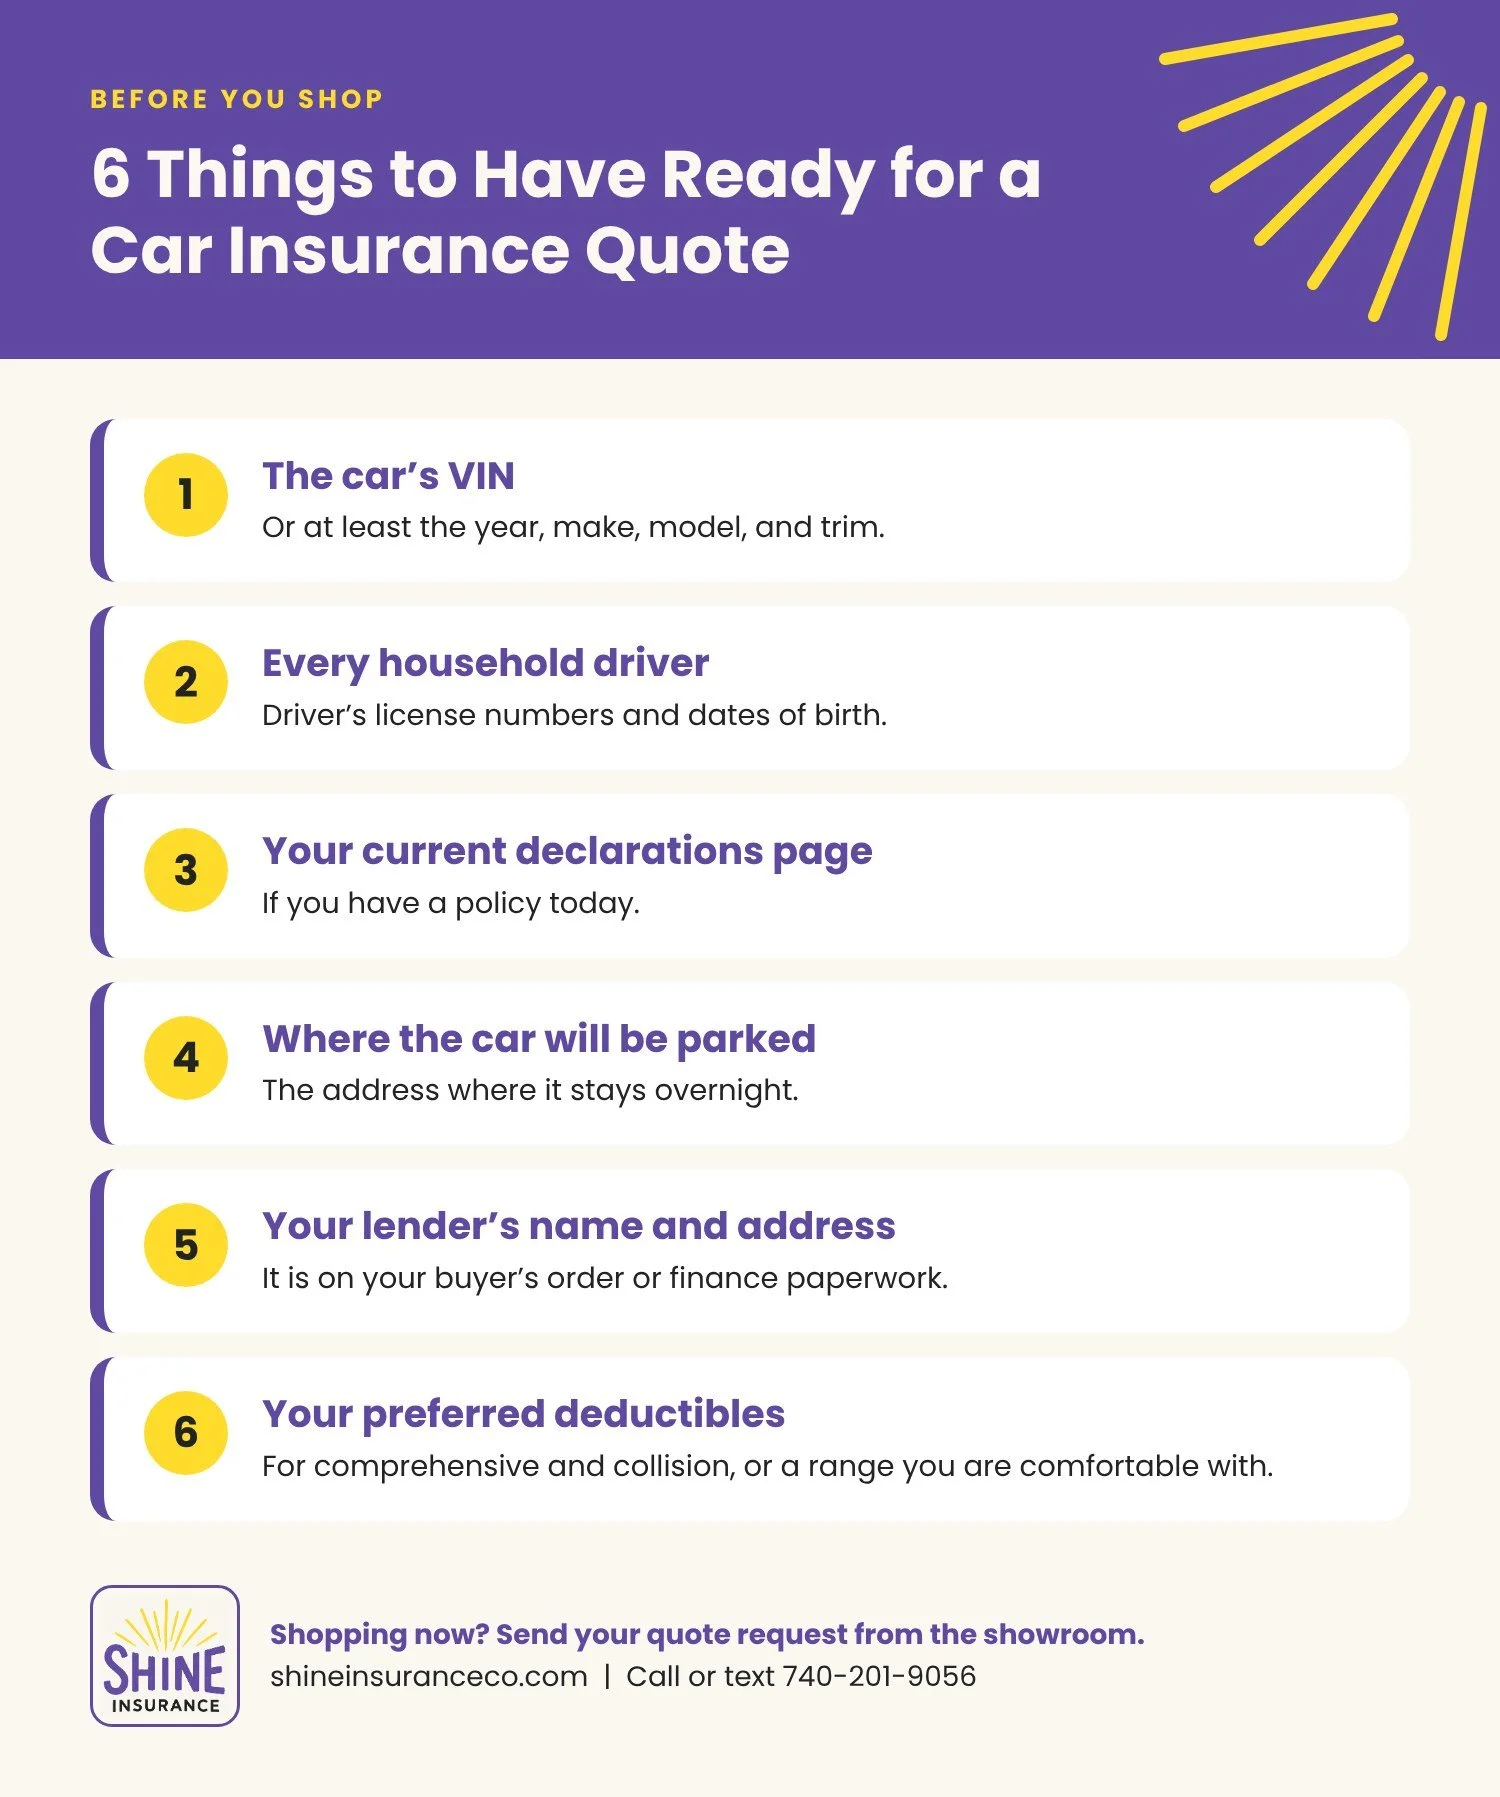
A quote goes fastest when you have the details in one place. Before you shop, or while you are still at the dealership, gather:
The VIN, or at least the year, make, model, and trim of the car you are considering
Driver's license numbers and dates of birth for every driver in your household
Your current policy's declarations page, if you have one
The address where the car will be parked overnight
The lender's name and mailing address, which will be on your buyer's order or finance paperwork
The deductibles you would like for comprehensive and collision, or a range you are comfortable with
If you are deciding between two cars, ask for quotes on both. Two vehicles with similar sticker prices can cost noticeably different amounts to insure, and it is better to know that before you sign than after.
Get the Quote Before You Reach the Finance Desk
The easiest way to avoid that Saturday afternoon stall is to get your insurance quote while you are still deciding on the car, not after.
That is exactly what Shine Insurance is built for. We are an independent agency, so we compare options from multiple carriers instead of offering a single company's price. We move fast once we have a completed quote request, and we work the hours car buyers actually shop. If the dealership is open, so are we, evenings and weekends included. When you are ready to buy, we can send proof of coverage, with your lender listed, straight to the dealership.
Ready When You Are
Shopping this week? Start your quote request here, or call or text us at 740-201-9056 from the showroom floor. Either way, you will know your insurance cost before you sign anything.
This article is general information about Ohio auto insurance and is not legal advice. Coverage depends on your policy language and the insurer's decisions. Your policy documents control.