
It is 7:15 on a Thursday night. The customer loves the car, the numbers work, the lender approved the deal, and everyone is smiling. Then the F&I manager asks for proof of insurance with the lender listed.
The customer's current insurer is closed for the night. The 800 number has a 40-minute hold. The quote that finally comes back is higher than the customer expected, and now the payment they were comfortable with an hour ago feels tight. The delivery gets pushed to Saturday. Sometimes Saturday never comes.
If you work in a dealership, you have lived some version of that night. Here is why the insurance step causes so much friction, and what it looks like to hand it off completely.
Why Insurance Becomes the Bottleneck
The insurance step is a problem for a simple reason. It is the one part of the deal that depends on a company that is not in the building.
The customer did not plan for it. Most buyers walk in thinking about the car and the payment. Very few have a quote on the specific vehicle before they arrive.
The lender will not wait. On a financed deal, the lender typically requires comprehensive and collision coverage with the lender listed as lienholder, and wants proof before funding. That requirement comes from the loan contract, so your F&I team cannot waive it.
The timing is wrong. Showrooms are busiest on evenings and weekends, which is exactly when many insurance offices are closed.
Price surprises kill momentum. Insuring a newer or higher-value car often costs more than what the customer pays today. When that number lands at the finance desk, it changes how the whole deal feels.
Ohio Law Puts the Final Check on Your Process
Here is a detail worth knowing. In Ohio, the temporary tag does not confirm insurance. Under ORC 4503.182(A), a temporary registration is issued on application and proof of purchase, and it is valid for 45 days. Nothing in that section requires proof of coverage.
Meanwhile, ORC 4509.101(A)(1) requires continuous proof of financial responsibility for anyone operating a vehicle in Ohio. So the legal obligation to be insured sits with the driver, and the practical checkpoint for whether a customer drives away insured is your delivery process. A clean, fast insurance handoff protects the customer, protects your lender relationships, and protects the deal.
What a Good Insurance Handoff Looks Like
Most dealerships do not want to be in the insurance business, and they should not have to be. What they need is a partner who makes the step disappear. Here is the standard we think every dealership should hold an insurance partner to:
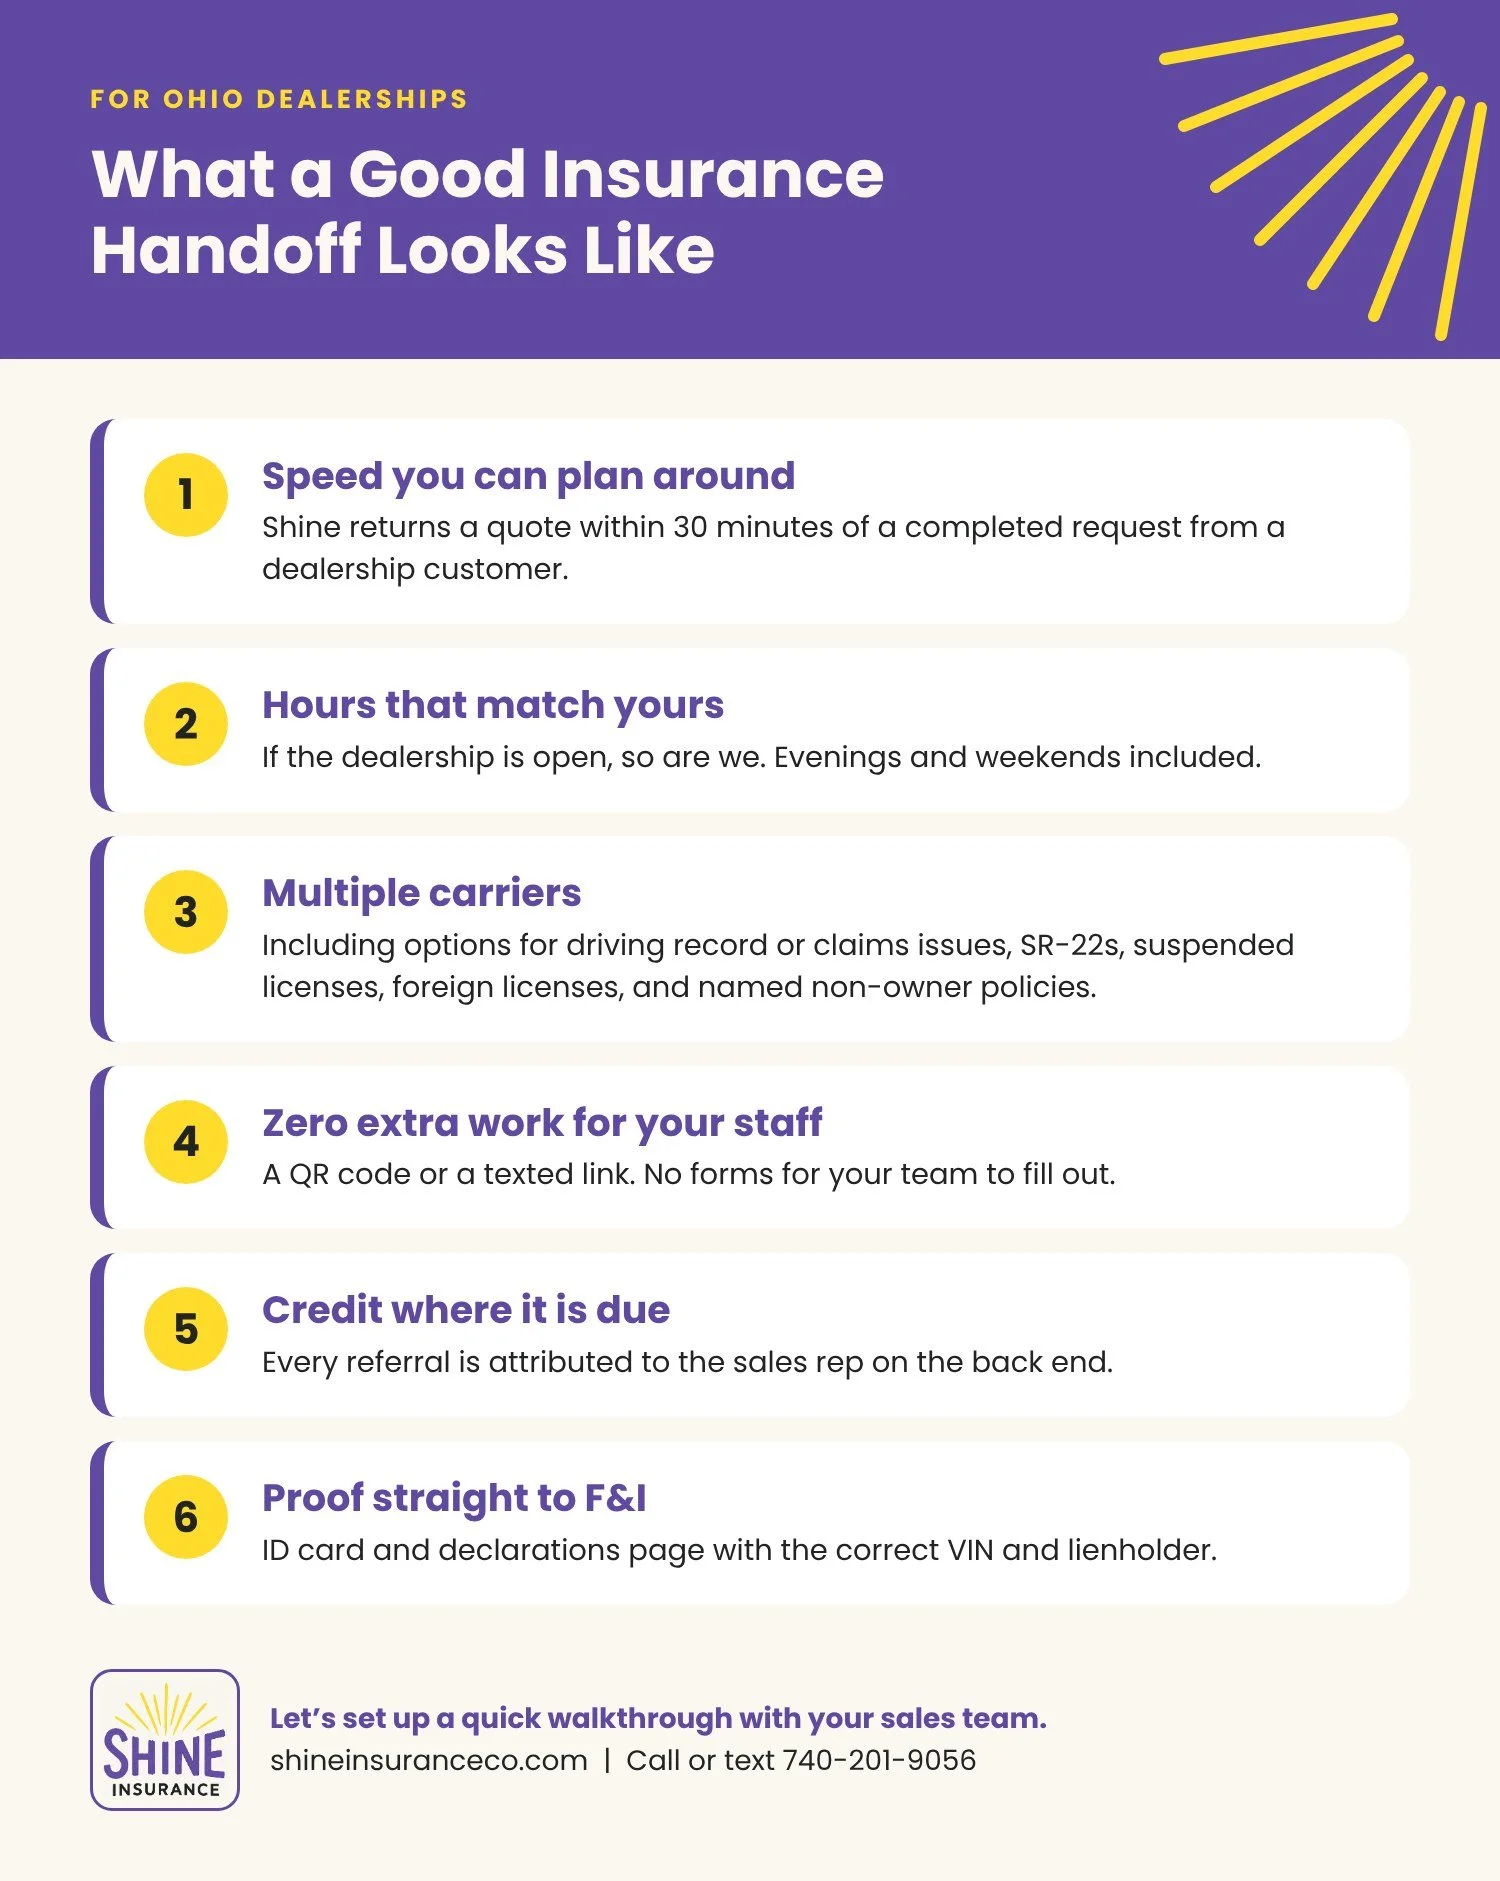
Speed you can plan around. A quote back fast enough that the customer is still at the desk. At Shine, we return a quote within 30 minutes of receiving a completed quote request from a dealership customer, and we aim for faster.
Hours that match yours. If you are open until 9 on weeknights and all day Saturday, your insurance partner should be too. Our rule is simple. If the dealership is open, so are we.
Multiple carriers, not one price. An independent agency can compare several companies for the same customer, which matters most for the customers who are hardest to place. Shine works with carriers that can help buyers with driving record or claims issues, customers who need an SR-22 filing or have a suspended license, drivers with a foreign license, and people who need a named non-owner policy.
Zero extra work for your staff. A QR code on the desk or a link the rep texts to the customer. No forms for your team to fill out and nothing new to track.
Credit where it is due. Your reps should get recognized for the customers they send. A good setup records which rep referred each customer on the back end, without anyone at the store keeping a list.
Proof delivered straight to F&I. The ID card and declarations page, with the correct VIN and lienholder, sent directly to whoever needs it.
Help Customers Show Up Ready
The best way to shorten the insurance step is to start it before the customer is at the desk. When a customer schedules an appointment or calls about a specific car, sending them a short guide helps them gather what they need. We have written three that any dealership is welcome to share:
Financing a Car in Ohio? What "Full Coverage" Your Lender Actually Requires
Quote the Car Before You Pick It: Why Two Similar Cars Can Cost Different Amounts to Insure
They are written for buyers, in plain language, and they do not steer anyone away from the products your F&I office offers.
What Working With Shine Looks Like
Shine Insurance works with dealerships across greater Columbus and Dayton. The setup is simple. We provide a QR code flyer and a quote request form built for your store, with your sales reps listed by name so every referral is attributed correctly. Your rep points the customer to the code, the customer fills out the form on their phone, and we take it from there. Your team goes back to selling cars.
Let's Talk About Your Store
If insurance has ever stalled a delivery at your dealership, we would love to show your team how this works. Call or text 740-201-9056 or reach out through our contact page, and we will set up a quick walkthrough with your sales team. Let's start building together!
This article is general information about Ohio auto insurance practices and is not legal advice.